Many small business owners protect their buildings, vehicles, equipment, and employees but overlook one of the fastest-growing areas of business risk: cybersecurity.
A company does not need to be a large technology firm to experience a cyber incident. Contractors, medical offices, retailers, professional service companies, restaurants, manufacturers, and local businesses can all store information that criminals may find valuable.
Small Businesses Can Be Attractive Targets
Smaller companies may have fewer cybersecurity resources than large corporations, making them an attractive target for criminals. A single compromised email account, stolen password, fraudulent payment request, or malicious attachment can create serious problems.
Cyber incidents can lead to lost data, interrupted operations, unauthorized transfers, legal expenses, customer notification costs, and damage to a company's reputation.
What Can Cyber Insurance Help Cover?
Coverage varies considerably between policies, but cyber insurance may provide protection for certain expenses associated with a covered cyber event.
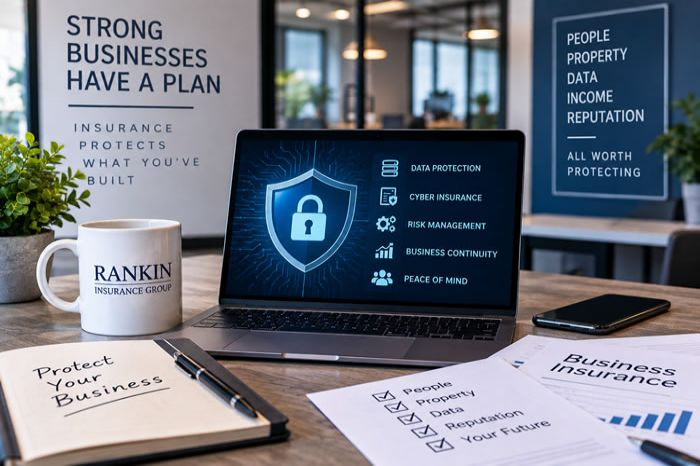
Depending on the policy, coverage may include data recovery expenses, computer system restoration, customer notification costs, credit monitoring services, legal assistance, cyber investigation expenses, business interruption, and certain ransomware-related expenses.
Cyber liability is one of several coverages that may be considered as part of a company's broader business insurance program.
Cyber Insurance Is Not a Replacement for Cybersecurity
Insurance should be part of a broader risk-management strategy rather than a substitute for good security practices.
Businesses should consider using multifactor authentication, strong password policies, employee training, secure backups, software updates, email filtering, and appropriate access controls. Companies should also have a plan for responding to a suspected breach.
Your Coverage Should Match Your Business
A professional office storing customer records may have different exposures than a construction company, restaurant, retailer, or manufacturer. The number of employees, type of information collected, payment systems used, and dependence on computer systems can all affect cyber risk.
Rankin Insurance Group can help North Carolina business owners evaluate their current commercial insurance program and determine whether cyber insurance should be part of their protection strategy. Businesses can also review the agency's complete range of insurance services when evaluating their overall coverage.
As technology becomes increasingly important to everyday business operations, understanding cyber risk is becoming just as important as protecting buildings, vehicles, and equipment.